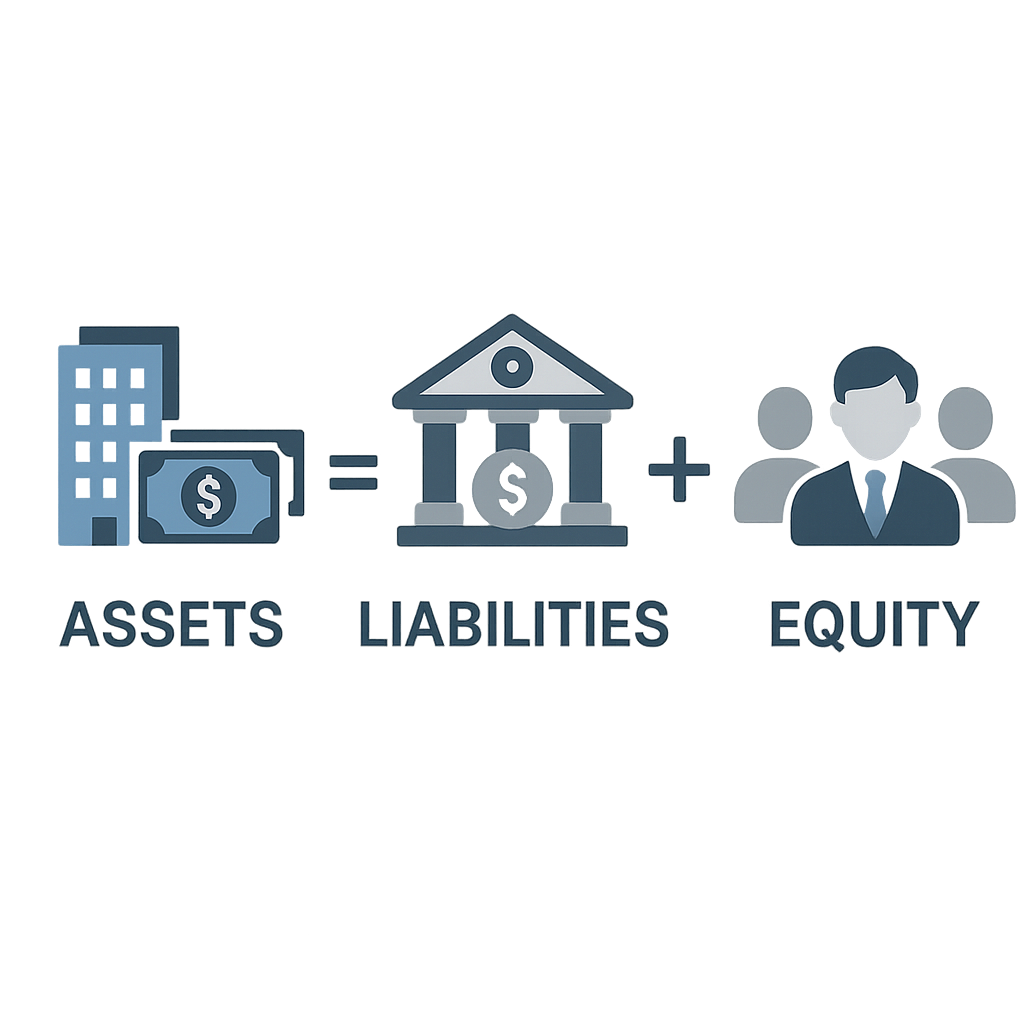
The accounting equation is the foundation of the balance sheet and double-entry bookkeeping: Assets = Liabilities + Equity. For a business owner, the value of the equation is not memorizing a formula. It is understanding how cash, debt, owner investment, profit, expenses, and withdrawals change the financial position of the business.
Net Profits Accounting Education
Accounting Equation Explained: Assets, Liabilities & Equity for Business Owners
Learn how the accounting equation connects your balance sheet, profit, debt, owner activity, and everyday transactions—and how to use it to ask better financial questions.
Last reviewed: September 8, 2026 | Author: Cornelius Frazier, MBA
The Net Profits Bottom Line
The accounting equation explains where the business’s resources came from. Assets are financed either by creditors through liabilities or by owners through equity. Profit generally increases equity over time, while losses and owner distributions can reduce it. The equation always needs to balance, but a balanced equation does not guarantee every transaction was categorized correctly.
The Fundamental Formula
Assets = Liabilities + Equity
What the Accounting Equation Actually Means
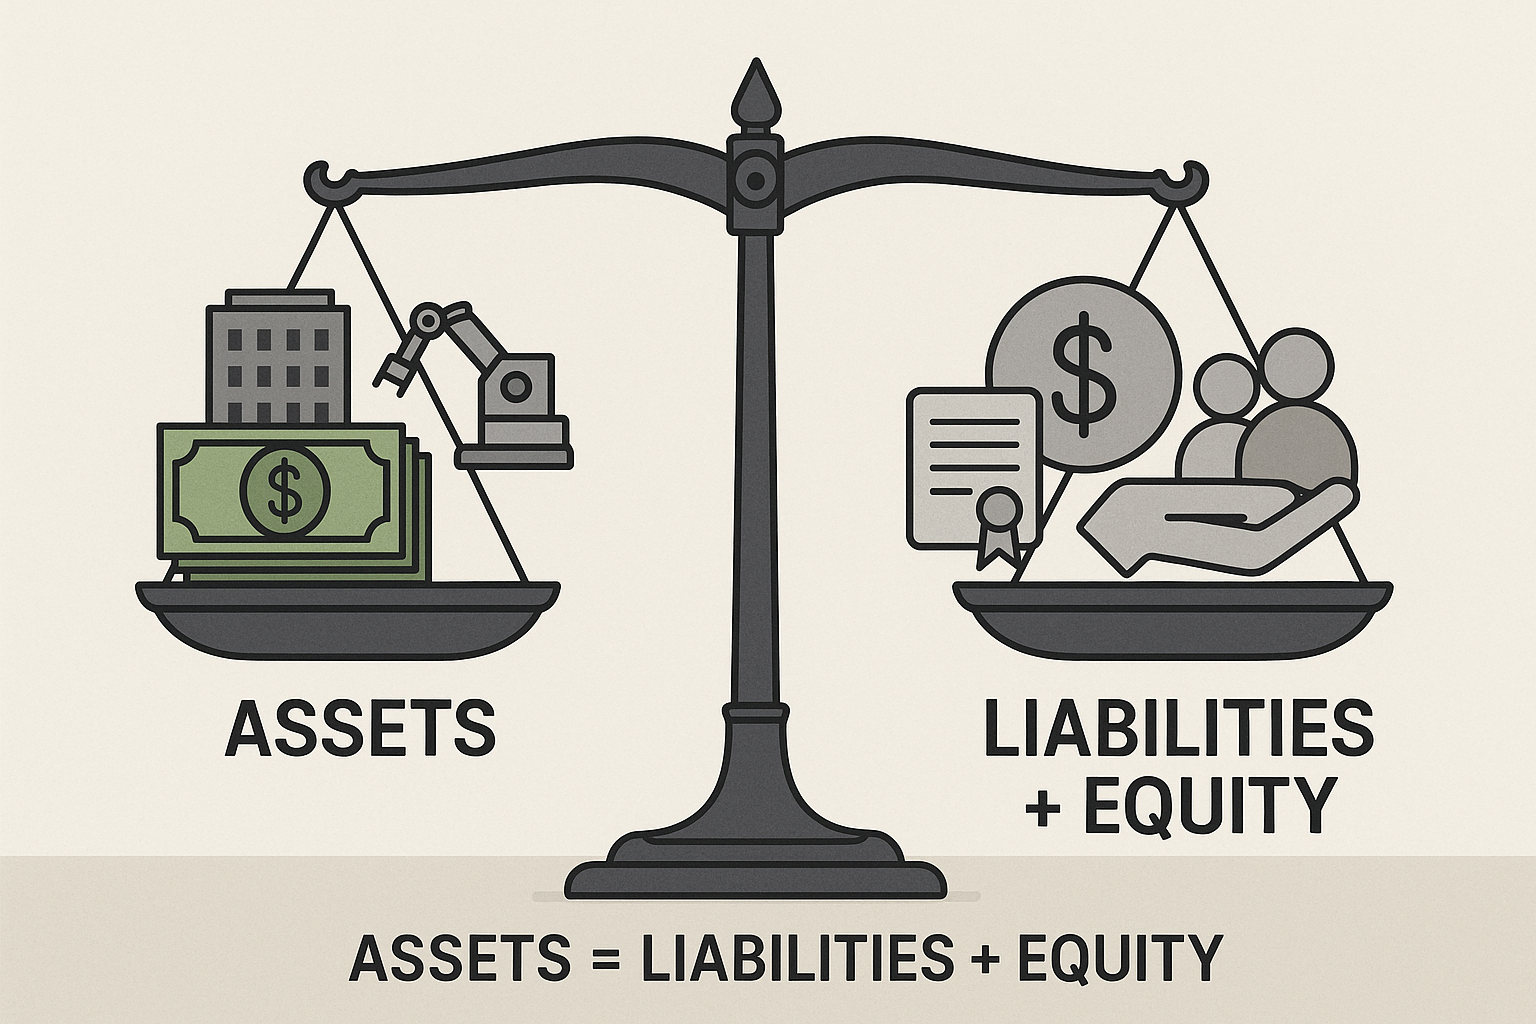
The equation describes the financial position of the business at a point in time. Everything the business controls or expects to benefit from is recorded as an asset. Claims against those assets belong either to creditors, which appear as liabilities, or to owners, which appear as equity.
If a business has $100,000 of assets and $40,000 of liabilities, the remaining $60,000 is equity:
Example
$100,000 Assets = $40,000 Liabilities + $60,000 Equity
You can also rearrange the equation:
- Equity = Assets – Liabilities
- Liabilities = Assets – Equity
The Three Parts of the Accounting Equation
Assets: What the Business Controls
Assets are resources expected to provide future economic benefit. Examples include cash, accounts receivable, inventory, equipment, vehicles, deposits, and certain intangible assets.
| Asset Type | Examples |
|---|---|
| Current assets | Cash, receivables, inventory, prepaid expenses |
| Long-term assets | Equipment, vehicles, buildings, long-term investments |
Liabilities: What the Business Owes
Liabilities are obligations to outside parties. They may include accounts payable, credit cards, payroll liabilities, taxes payable, loans, financing agreements, and customer deposits that have not yet been earned.
Equity: The Owners’ Residual Interest
Equity represents the owners’ residual interest after liabilities are subtracted from assets. The exact equity accounts depend on the entity type. A sole proprietor may use owner capital and owner draws, while a corporation may use common stock, additional paid-in capital, retained earnings, and distributions or dividends.
If your chart of accounts is designed properly, these balance-sheet categories are much easier to maintain and understand.
How Everyday Transactions Change the Equation
The fastest way to understand the accounting equation is to follow real transactions. Each transaction changes at least two accounts, but total assets must continue to equal liabilities plus equity.
| Transaction | Asset Effect | Liability Effect | Equity Effect |
|---|---|---|---|
| Owner invests $25,000 cash | +$25,000 | — | +$25,000 |
| Business borrows $15,000 | +$15,000 | +$15,000 | — |
| Buys $8,000 equipment for cash | Cash -$8,000; Equipment +$8,000 | — | — |
| Earns $5,000 revenue in cash | +$5,000 | — | Increases through income |
| Pays $2,000 operating expense | -$2,000 | — | Decreases through expense |
Important distinction
Revenue and expenses affect equity through net income. In a corporation, net income ultimately closes into retained earnings. In a sole proprietorship, it ultimately affects owner capital. The exact bookkeeping path depends on the entity and accounting system.
The Expanded Accounting Equation
The expanded equation makes the relationship between the income statement and balance sheet easier to see. For a simple owner-managed business, one teaching version is:
Assets = Liabilities + Owner Capital + Revenue – Expenses – Draws
The point is not that every business literally uses those exact equity account names. The point is that profit and owner activity explain why equity changes from one period to the next.
Separate example: Assume a business begins with $80,000 of owner capital, earns $60,000 of revenue, incurs $30,000 of expenses, and the owner takes $10,000 of draws. There are no other equity changes. Calculate profit, the change in equity, and ending equity separately:
- Net income: $60,000 revenue − $30,000 expenses = $30,000.
- Increase in equity: $30,000 net income − $10,000 owner draws = $20,000.
- Ending equity: $80,000 beginning capital + $20,000 increase = $100,000.
The $10,000 draw reduces equity; it is not an operating expense in this example.
How the Accounting Equation Connects to Double-Entry Bookkeeping
Double-entry bookkeeping records each transaction with equal debits and credits. The debit-and-credit system is what keeps the accounting equation in balance.
- Assets and expenses normally increase with debits.
- Liabilities, equity, and revenue normally increase with credits.
- Total debits must equal total credits for each journal entry.
This is why software such as QuickBooks can produce a balance sheet automatically when transactions are recorded correctly.
Balanced does not mean correct
A transaction can be posted to the wrong expense account and the equation will still balance. The same is true if a loan payment is split incorrectly between principal and interest. Reconciliations, documentation, review, and a sensible chart of accounts are still essential.
What Business Owners Can Learn From the Equation
The accounting equation becomes more useful when you stop treating it as a homework formula and start using it to ask business questions.
Debt Load
Are liabilities growing faster than assets or equity?
Owner Value
Is equity increasing because the business is generating profit—or mainly because owners keep adding cash?
Liquidity
How much of the asset base is actually available to pay near-term obligations?
Financing
Is growth being funded through debt, retained profit, or additional owner investment?
Useful related measures include:
- Working Capital = Current Assets – Current Liabilities
- Current Ratio = Current Assets ÷ Current Liabilities
- Debt-to-Equity Ratio = Total Liabilities ÷ Total Equity
- Return on Equity = Net Income ÷ Average Equity
These ratios need context. A “good” debt-to-equity or current ratio varies by industry, business model, seasonality, and stage of growth. Use them as trends and decision tools rather than universal pass/fail scores.
You can also use the Net Profits business calculators to work through profitability, break-even, cash-flow, and other financial questions.
Common Accounting Equation Mistakes
- Confusing an asset purchase with an immediate expense. Some purchases provide benefits over multiple periods and may need to be capitalized and depreciated rather than expensed immediately.
- Ignoring owner contributions and distributions. Owner cash going into or out of the business is not automatically revenue or expense.
- Recording loan proceeds as revenue. Borrowed money generally increases cash and a liability; it is not operating income.
- Recording an entire loan payment as expense. Principal reduces the liability; interest is generally the expense component.
- Assuming a balanced balance sheet means clean books. Incorrect classifications can still preserve mathematical balance.
- Mixing business and personal activity. This makes equity, expenses, and cash harder to interpret and weakens financial readiness.
For a broader cleanup process, see the Small Business Financial Readiness Checklist.
A 10-Minute Monthly Accounting Equation Review
- Review the balance sheet. Look at total assets, total liabilities, and total equity.
- Compare to the prior month. Identify large changes rather than only looking at ending balances.
- Inspect new liabilities. Confirm loans, credit cards, taxes payable, and other obligations are recorded properly.
- Review owner activity. Confirm contributions, draws, and distributions did not get posted as revenue or operating expense.
- Reconcile cash and credit cards. A mathematically balanced equation does not replace reconciliation.
- Compare profit to equity changes. Large unexplained differences may point to owner activity, prior-period adjustments, or classification issues.
Cornelius’ Take
Business owners do not need to become accountants, but they should understand what the balance sheet is telling them. Once you understand that every asset was funded by either debt or equity, borrowing, owner contributions, profit, and withdrawals become much easier to interpret.
Practical Next Step
Pull your most recent balance sheet and calculate Equity = Assets – Liabilities. Then compare that equity balance with the prior month or prior year. Ask what actually caused the change: profit, losses, debt, owner contributions, distributions, or accounting adjustments.
Tools That Fit This Workflow
QuickBooks is the strongest fit for this topic because the accounting equation is built into the double-entry bookkeeping behind the balance sheet. If you use QuickBooks, the key is not simply having the software—it is setting up the chart of accounts correctly, reconciling accounts, and reviewing reports consistently.
Affiliate disclosure: Net Profits Consulting may earn compensation if you purchase through certain partner links, at no additional cost to you. We recommend tools based on relevance to the business problem discussed.
Accounting Equation FAQs
What is the accounting equation?
The basic accounting equation is Assets = Liabilities + Equity. It is the mathematical structure behind the balance sheet.
Why must the accounting equation balance?
Double-entry bookkeeping records equal debits and credits, so every transaction preserves the relationship between assets, liabilities, and equity.
Does a balanced accounting equation mean the books are accurate?
No. A transaction can be posted to the wrong accounts and still keep the equation balanced. Reconciliations and review are still necessary.
How does profit affect the accounting equation?
Profit increases equity, while a net loss reduces equity. In corporations, net income ultimately closes into retained earnings. In owner-managed entities, it ultimately affects the appropriate capital accounts.
Is cash the same thing as equity?
No. Cash is one asset. Equity is the residual value of all assets after liabilities are deducted. A profitable business can have low cash, and a business with plenty of cash can still carry substantial debt.
Need Cleaner Books?
Turn the Accounting Equation Into Useful Financial Reports
Net Profits Consulting can help with bookkeeping cleanup, QuickBooks setup, reconciliations, chart-of-accounts design, financial reporting, and ongoing accounting support.
Cornelius Frazier, MBA
Founder, Net Profits Consulting · Business Consultant · Operations Strategist · Certified Business Educator. Cornelius holds a BA in Accounting and an MBA and brings more than two decades of business and financial experience to practical small-business education.